 Ghana Mining Review A reliable source of mining industry news in Ghana

Related Articles

Across Africa’s mineral-rich heartlands, the traditional deal between sovereign states and global mining conglomerates is being aggressively renegotiated. Driven by geopolitical competition for critical minerals and frustration over decades of raw commodity exports, governments from Zambia’s copper belt to Ghana’s gold fields are telling foreign investors that access to underground wealth now comes with far steeper conditions.
Zambia has emerged as a major frontrunner in this continental shift. Positioned at the center of the global rush for energy-transition metals, Lusaka has spearheaded aggressive local-content mandates including strict local procurement quotas and demands for domestic copper refining to break the traditional “pit-to-port” model. By leveraging its critical copper and cobalt reserves to force foreign capital into funding local supply chains and in-country processing, Zambia is setting a powerful precedent for resource nationalism across Sub-Saharan Africa.
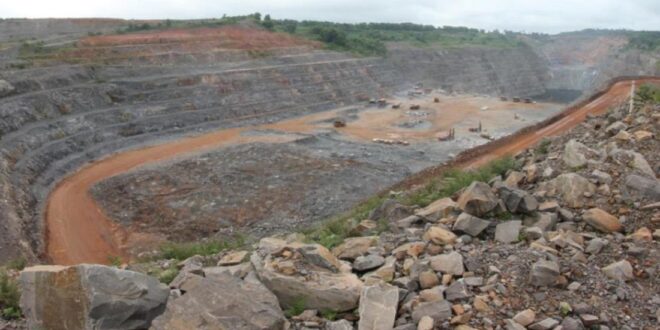
Ghana is now applying a similar playbook in the gold sector, creating a high-stakes test case for investor confidence. Publicly, Accra has maintained deliberate ambiguity over the lease renewal for Gold Fields Ltd.’s Tarkwa mine one of the country’s largest and most productive gold assets, accounting for nearly 20% of the South African miner’s global output. Officials insist that any extension must deliver significantly higher economic returns and deeper domestic ownership.
“It won’t be business as usual where we just automatically renew the lease,” Minerals Commission Head Isaac Andrews Tandoh said, signaling that the government is leveraging its regulatory leverage to extract stronger investment commitments.
The government’s tough stance follows its recent decision regarding the nearby Damang mine. After Gold Fields deprioritized the asset, Ghana redirected the concession to Engineers & Planners, a domestic mining firm led by Ibrahim Mahama. While Damang was an underperforming asset, the move underscored a growing appetite to transfer strategic mining operations to local players a trend that has heightened anxiety among foreign investors watching the Tarkwa negotiations.
Replacing an operator of Gold Fields’ scale at Tarkwa, however, carries profound transition risks given the mine’s capital-intensive nature and complex operational requirements. Industry analysts warn that governments must carefully navigate the thin line between resource nationalism which seeks to maximize domestic value and investment nationalism, which risks scaring off the mobile global capital required to extract minerals in the first place.
“Governments are entitled to renegotiate the mining bargain as economic realities evolve,” noted an industry report on African mining frameworks. “And investors increasingly recognize that their licence to operate depends on delivering broader domestic value. But there is an important distinction between resource nationalism and investment nationalism. Confusing the two would be an expensive mistake.”
As African states negotiate from a position of unprecedented geopolitical leverage, the outcome in key markets like Zambia and Ghana will determine whether the continent can successfully force foreign miners into high-value partnerships without sacrificing the long-term investment capital their economies rely upon.